

Till: Debit Card for Kids
Till Financial
- 4.5
- 317.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
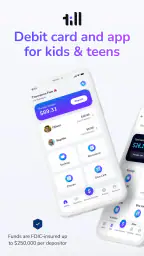
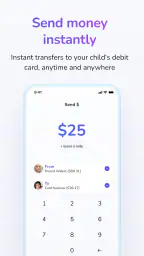
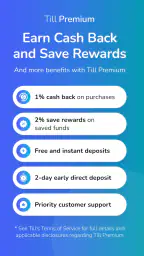
Till: Debit Card for Kids Pros and Cons
Pros
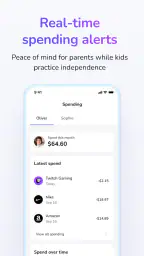
- Parents can set spending limits and monitor purchases in real time.
- Kids can learn money management through controlled everyday spending.
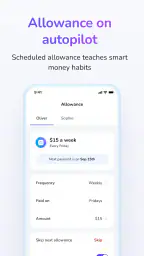
- The app supports allowance payments and recurring transfers.
- Parents can quickly lock or unlock the connected debit card.
- Transaction notifications help families spot unfamiliar activity promptly.
Cons
- Some features may require a paid subscription or additional fees.
- Availability and card benefits can vary by country or region.
- Younger children may still need guidance to use the app responsibly.
- A smartphone and reliable internet connection are required for management.
- Cash-based spending is less convenient to track than card transactions.
 Analysis by All-app
Teaching a child to handle money is much easier when the lesson happens during ordinary purchases rather than in a one-time conversation. I found Till: Debit Card for Kids most useful in exactly that role: it gives families a finance app and debit card experience designed for kids and teens, while leaving the adult involved in the process. The goal is not simply to let a young person spend independently. It is to make spending visible, discussable, and gradually more deliberate.
Till Financial develops the app, which is available as a free finance app for Everyone. Its store presence shows a 4.5 average from around 2.2 thousand ratings, with more than 100 thousand installs. Those figures suggest a product that has attracted real interest from families, although they do not replace the more important question: whether its approach fits the way your household wants to teach money habits.
How Till fits into a family’s everyday money routine
The basic workflow is straightforward. An adult and a young person use the app as the shared place to manage the debit-card relationship, while the child or teen gets practical experience making spending decisions. I would not treat it as a miniature adult bank account that removes parental involvement. Its value comes from using the card and the app together as a learning routine.
A realistic example is a teenager going out with friends after school. Instead of handing over cash or approving every purchase in person, a parent can use the family’s agreed routine around the card and then review what happened afterward. The useful conversation is not only “How much did you spend?” It can be “Which purchase mattered most to you?” or “Would you make the same choice next week?” That turns a transaction into a small budgeting lesson without making every purchase feel like an interrogation.
I also see a good fit for younger users who are moving away from cash. Cash can make money feel concrete, but it is awkward to track once it is split across pockets, bags, and forgotten change. A card-based routine gives the child a consistent way to pay, while the app gives the family a shared reference point. For a parent, that can be less work than trying to reconstruct several small cash payments.
The important distinction is that Till is not just a spending tool for children. It is a supervised bridge between allowance-style money and the more independent financial decisions that arrive later. That makes the app most effective when the adult sets expectations before the card is used: what the money is for, when the balance is reviewed, and what happens if the child spends too quickly.
The strongest result comes from pairing the app with a repeatable family habit, not from handing over the card and forgetting about it. A short weekly check-in can be enough. Look at recent activity together, identify one choice that worked, and decide whether anything should change. Keeping this routine calm matters because a child who expects every review to become a lecture may stop engaging with the process.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Who gets the most from the setup
Till makes particular sense for parents who want a middle ground between unrestricted cash and approving every single purchase. It can also suit families with children at different stages of independence, because the same general system can support a younger child who needs close guidance and an older teen who mainly needs occasional oversight.
It is less appealing if your family already has a simple cash allowance system that everyone understands and nobody finds inconvenient. It may also be the wrong choice for a household looking for a full personal-finance platform with detailed investing, bill management, or adult banking tools. The product’s focus is narrower and more practical: helping kids and teens become smarter spenders through a debit card and app.
Settings and agreements worth checking first
Before the first purchase, I would spend time reviewing the available family controls and agreeing on how they will be used. The exact options visible to you can depend on the current app experience and account setup, so the sensible approach is to open each relevant control rather than assume a setting works a certain way. The key question is not merely what can be restricted, but who is responsible for checking the result.
Start with spending boundaries. If your child has a regular amount available, decide whether that money is intended for snacks, entertainment, school-related needs, or a mixture. A vague arrangement creates arguments later because the same purchase can look reasonable to the child and unnecessary to the parent. Writing down a few examples in plain language is surprisingly useful.
Next, agree on the review rhythm. Daily checking may be appropriate for a child who is just learning, but it can feel intrusive for an older teen. A weekly review often creates a better balance: recent spending is still fresh, while the young person has room to make ordinary choices. If there is a larger purchase, discuss it before the card is used rather than relying on a surprise conversation afterward.
Notifications and account activity are worth treating as teaching prompts rather than alarms. When a parent sees a transaction, the best response is not automatically to challenge it. Ask whether the purchase matched the plan and whether the child understands its effect on the remaining balance. This helps separate an honest mistake from a deliberate choice and gives the child a chance to explain the context.
Another setting-related habit is checking the app after updates. Till is currently listed as version 162.40.1 and supports Android 7.0 or later. That broad Android compatibility is helpful for families using older phones, but an older device can still produce a less comfortable experience than a recent one. I would keep the app updated where possible and confirm that the parent’s phone and the child’s device both behave properly before relying on the card for an important outing.
Because the app is free to download but includes in-app purchases ranging from $7.99 to $79.00 per item, I would also review any purchase-related prompts carefully. A child should understand which actions are part of the normal card routine and which may involve an additional charge. The adult should be the person making that decision, not the child tapping through a screen quickly.
Small routines that make the app faster to live with
Experienced users will get more from Till by standardizing the moments around it. For example, choose one day for the weekly balance conversation and one place where the card is kept when it is not being used. That sounds minor, but it prevents the common problem of turning money management into a series of urgent searches and last-minute messages.
I would also use a simple three-question review: what did you buy, why did you buy it, and would you buy it again? These questions are faster than reviewing every transaction in detail, yet they reveal whether the child is spending from a plan or simply reacting to whatever is happening that day. Over time, the answers can guide a more realistic allowance arrangement.
For teens, the faster pattern is to let them lead the review. Ask them to explain their recent spending before offering an opinion. This shifts the app from a parental surveillance tool to a record the young person can interpret. It also exposes misunderstandings early, such as assuming that a balance will recover automatically or treating available money as unlimited.
For younger children, use concrete categories instead of financial jargon. “School lunch,” “fun,” and “saving for something” are easier starting points than abstract budget labels. The app can support the conversation, but the language used by the family determines whether the child actually learns from it.
One non-obvious advantage of a repeatable card routine is that it creates a natural pause before spending. The child knows that purchases will be visible later, which can encourage a moment of thought without requiring the parent to stand beside them. That is not the same as a formal budgeting system, but it is a useful behavioral nudge for everyday decisions.
Where the limits become important
The biggest limitation is that no app can decide how much independence is appropriate for a particular child. A debit card may provide structure, but it does not automatically teach saving, comparison shopping, or recognizing pressure from friends. Those skills still need conversation and practice. If the adult never reviews the activity, the educational benefit is much smaller.
There is also a trade-off between convenience and control. The more closely a parent monitors every purchase, the more predictable the spending becomes, but the less opportunity the child has to practice judgment. On the other hand, giving broad freedom too early can turn the card into a source of avoidable mistakes. I would increase independence in stages, based on how the child handles previous decisions rather than on age alone.
Families should also think about what happens when the phone is unavailable. A child may need to use the card during travel, at school, or while visiting relatives, so the household should agree on a backup plan for questions about spending. The app is useful as the central routine, but it should not be the only way the family knows what the child is allowed to do.
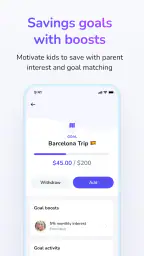
Another practical limitation is that a debit-card learning system is not ideal for every type of money lesson. If your main goal is teaching a child to save physical cash, compare prices in a shop, or understand a detailed household budget, you will need activities outside Till. I would combine it with a simple savings goal or a written spending plan rather than expecting the app to cover every financial concept.
Parents should also be realistic about the emotional side. A declined or questioned purchase can feel embarrassing to a child, especially around friends. Before giving the card an important role in social situations, explain what the child should do if a payment does not go as expected and how to contact the adult. A clear plan reduces panic and makes the system feel supportive rather than punitive.
How it compares with cash and general banking apps
Compared with cash, Till offers better visibility for families who want spending to be part of an ongoing conversation. Cash is wonderfully tangible and can be easier for very young children to understand, but it is harder to review accurately. Till is the better fit when the child is ready to use a card and the parent wants a consistent digital record of the routine.
Compared with simply adding a child to an adult banking setup, Till has a clearer educational purpose. A general bank app may be convenient for the parent, but it can expose a young user to a broader financial environment without giving the family a focused way to discuss spending behavior. Till’s narrower focus is a strength for families that want the card to be part of a guided learning process.
On the other hand, a general banking option may be preferable for an older teen who needs features beyond supervised spending and is ready to manage more of their financial life independently. The right choice depends on whether the priority is gradual coaching or a wider transition toward adult banking. Till works best in the stage between those two extremes.
My verdict after using it as a teaching tool
I recommend Till to parents who want a practical, structured way to introduce card spending without treating independence as an all-or-nothing decision. Its free entry point, child-and-teen focus, and connection between a debit card and a finance app make it approachable for families starting this conversation. The app is especially useful when paired with a weekly review, clear spending expectations, and gradually changing levels of oversight.
I would skip it if you want a comprehensive adult finance platform, if your family strongly prefers cash, or if nobody has time to participate in the routine. The card alone cannot create good habits. It becomes worthwhile when the adult uses transactions as prompts for short, respectful conversations and lets the child take increasing responsibility.
For me, the best way to use Till: Debit Card for Kids is to treat it as training wheels rather than a permanent substitute for financial judgment. Begin with clear rules, review real purchases, and loosen control only when the child shows consistency. Used that way, it can make money lessons feel connected to everyday life instead of turning them into abstract advice.
The app is rated for Everyone, and its current version is 162.40.1. With Till Financial behind it and a growing user base, it is a credible option for families exploring supervised spending. My final advice is simple: decide what lesson you want the card to teach before you activate the routine. If that lesson is thoughtful, gradual independence, Till is a sensible tool to put in the child’s hands.
Frequently Asked Questions
What is Till: Debit Card for Kids, and how does it work?
Till is a family-focused debit card and money-management app designed to help children learn about spending, saving, and budgeting under a parent’s supervision. Parents typically create and manage the account, add funds, review transactions, and set expectations, while the child uses the card for approved purchases. Availability, account features, and eligibility may vary by location and current provider policies.
What age is Till suitable for, and does a parent need to approve the account?
Till is intended for children and teenagers, so it is not an independent adult banking product. A parent or legal guardian generally needs to open the family account, provide required information, and remain responsible for managing the child’s card and activity. Before downloading, check the latest age requirements, supported countries, identity-verification rules, and whether both parent and child need compatible devices.
Are there spending limits or parental controls on the Till card?
The app is designed to give parents oversight of a child’s spending, which may include reviewing transactions, adding money, setting allowances, and controlling how funds are used. Exact controls can depend on the plan, card type, merchant category, and region. Parents should explore the current settings after registration and understand that controls may not prevent every attempted transaction or replace regular communication about responsible spending.
Are there fees for using Till: Debit Card for Kids?
Costs may apply depending on the Till plan, card order, delivery method, account funding method, replacement requests, or other optional services. Pricing and fee structures can change, and some features may be limited to paid memberships. Review the official pricing information and the terms shown during sign-up before committing, paying particular attention to recurring charges, cancellation rules, ATM usage, and any fees associated with international or unsupported transactions.
Is Till safe for children, and what happens if the card is lost or misused?
Till includes a parent-managed environment intended to make children’s spending more visible and controlled than using cash alone. However, parents should still enable device security, protect login details, and regularly review activity. If the card is lost, stolen, or used without permission, freeze or lock it through the app as soon as possible and contact Till support. Also check the provider’s dispute, replacement, and liability policies before relying on the card.


